Private Health Insurance in Norway: Is It Worth the Extra Cost?
You have finally moved to Norway, settled into your cozy apartment, and started navigating the local rhythms of life, only to realize that getting a simple specialist referral feels like trying to book a table at a Michelin-star restaurant during the height of tourist season. I remember waiting nearly five months for a basic dermatological check-up, staring at my phone in disbelief as the weeks turned into seasons. This guide explores whether paying for private health insurance is a genuine necessity or an avoidable expense for expats living in Norway.
Understanding the Foundation: Norway’s Public Healthcare System
Before we can even talk about whether private insurance is "worth it," we have to understand the massive, taxpayer-funded engine that is the Norwegian public health system. Most people arriving from countries with entirely private systems, like the United States, or even mixed systems like Germany, are often surprised by how the Healthcare in Norway for Expats: How the System Works (2027) actually functions. It is built on the principle of universal access, meaning that once you are a legal resident and a member of the National Insurance Scheme (Folketrygden), you are entitled to care.
However, "entitled to care" does not mean "immediate care for all things." The public system is designed around a gatekeeper model. This is where The Fastlege Scheme: Navigating Norway’s GP System comes into play. Your GP (Fastlege) is the person who decides if your ailment is serious enough to warrant a specialist’s time. If you have a life-threatening emergency, the system is world-class and moves with incredible speed. But if you have a "non-urgent" issue, such as a nagging sports injury or a non-cancerous skin condition, you might find yourself at the bottom of a very long list.
The financial side of the public system is also unique. While care isn't "free," it is heavily subsidized. You pay small user fees (egenandel) for every consultation and prescription until you hit a specific annual ceiling. This is a crucial concept for expats to grasp, as detailed in our guide on Healthcare Budgeting: The Frikort Exemption Card and User Fees. Once you hit that limit, usually around 3,000 to 3,500 NOK, you get an exemption card. Understanding the Frikort: The 2026 Healthcare Exemption Card Limit is vital because it sets the "baseline" cost of your health. If you are healthy, you might only spend a few hundred kroner a year. If you are chronically ill, your costs are capped. Private insurance, then, isn't about saving money on the care itself; it's about buying your way out of the waiting room.
What is Private Health Insurance in Norway?
In Norway, private health insurance (behandlingsforsikring) is not an alternative to the public system, but rather a supplement to it. Even if you have the most expensive private policy in the world, you will still be a member of the National Insurance Scheme. If you are in a car accident or suffer a heart attack, the ambulance is still taking you to a public hospital. Private insurance essentially exists to handle everything that isn't an immediate threat to your life or limb.
There are generally two ways expats encounter private insurance. The first is through their employer. It has become increasingly common for Norwegian companies to offer private health insurance as a perk to attract talent, especially in the tech and energy sectors. If your contract includes this, you are in luck—it's a massive benefit that usually covers your family as well. The second way is by purchasing an individual policy. This is where you have to weigh the monthly premiums against the potential benefits.
For many foreigners, especially those who travel frequently or aren't yet fully integrated into the local registry, international providers like Cigna Global offer a sense of continuity that local Norwegian insurers might not. These international plans are often more comprehensive and include coverage for medical evacuation or care in your home country. On the other hand, for digital nomads or those on shorter stays, a provider like SafetyWing can offer a more flexible, subscription-based model that covers both travel and basic medical needs without the long-term commitment of a traditional Norwegian policy.
The Reality of Waiting Lists and Specialist Access
The single biggest argument for going private in Norway is the time factor. While the quality of medical professionals in the public sector is exceptionally high, the administrative bottleneck is real. When your GP sends a referral, it goes to a regional health authority that triages your case. If they deem your condition "chronic but not acute," you could be looking at a wait time of several months. This is a recurring theme in Specialist Referrals in Norway: How the Waiting Times Work.
Imagine you are a professional whose work depends on being physically active, and you develop a repetitive strain injury. In the public system, getting an MRI and seeing an orthopedic specialist might take twelve weeks. During those twelve weeks, your productivity drops, your stress increases, and the injury might even worsen. With private insurance, or by paying out-of-pocket at a private clinic like Volvat or Aleris, you could often have that MRI tomorrow and see a specialist the day after.
This speed is particularly relevant when it comes to Mental Health in Norway: Accessing Therapy and Psychiatric Care. The public mental health system is under significant strain, and unless you are in a state of acute crisis, the wait for a psychologist can be dishearteningly long. Private insurance often includes a set number of sessions with a psychologist or psychiatrist, allowing you to bypass the public queue entirely. For many expats dealing with the stress of relocation and cultural adjustment, this immediate access is the primary reason they find private cover "worth it."
Comparative Cost Analysis: Public vs. Private
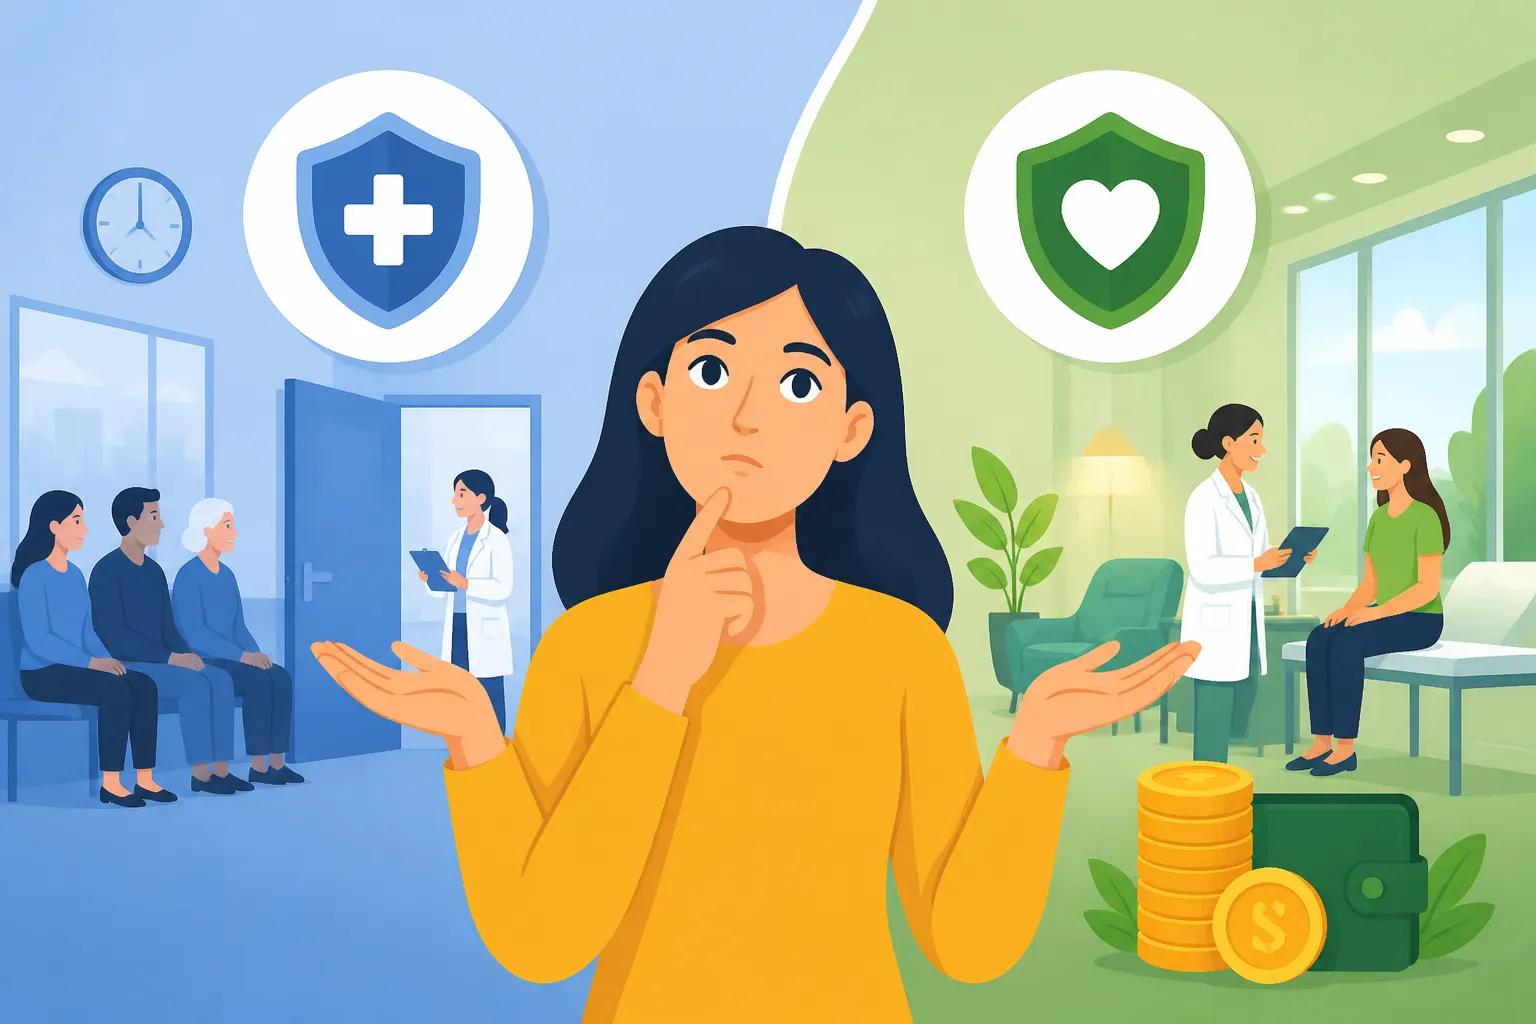
To decide if the extra cost is justified, we need to look at the numbers. The public system is essentially "pre-paid" through your taxes (roughly 7.9% of your gross income goes to social security contributions). The private system requires an additional monthly premium.
| Feature | Public Healthcare (Folketrygden) | Private Health Insurance |
|---|---|---|
| Monthly Premium | Included in taxes | 500 – 1,500 NOK (Individual) |
| Specialist Wait Times | Weeks to months | 2 – 10 days |
| GP Access | Must use assigned Fastlege | Choice of any private GP |
| User Fees | Up to the Frikort limit | Often 0 or very low |
| Choice of Hospital | Limited (Patient Choice rules apply) | Any private facility in network |
| Physiotherapy | Requires referral, long waits | Direct access usually included |
For a healthy 30-year-old, a private insurance policy might cost around 600 NOK per month. Over a year, that’s 7,200 NOK. If you don’t get sick or injured, that’s 7,200 NOK "wasted." However, if you need a single minor surgery that would have had a six-month wait in the public system, that 7,200 NOK suddenly feels like the best investment you’ve ever made.
For those who are not yet eligible for full Norwegian benefits, such as those on a D-number, the math changes. You might find that Healthcare Rights for D-Number Holders: Exclusions and Alternatives make private insurance more of a necessity than a luxury. In these cases, a plan from Cigna Global can bridge the gap, ensuring you aren't hit with massive bills if you need non-emergency care before your Fødselsnummer (national identity number) is issued. Similarly, SafetyWing can be a literal lifesaver for those in the "in-between" phase of residency.
The Comfort Factor and Patient Choice
Beyond speed, there is the question of the "patient experience." Norwegian public hospitals are clean, modern, and efficient, but they are still large public institutions. You might be in a shared room, and the food will be standard institutional fare. Private clinics, however, often feel more like high-end hotels. You get a private room, more personalized attention, and often a higher degree of continuity with the same doctor.
This comfort factor extends to how you interact with the system. If you use a private provider, you often don't need a referral from a GP to see a specialist. You can simply book an appointment online and show up. For an expat who might still be struggling with the nuances of The Fastlege Scheme: Navigating Norway’s GP System, the simplicity of the private route is a huge relief. There is no need to "convince" a GP that your problem is serious enough; if you are willing to pay (or your insurance is), you get seen.
Furthermore, many international policies, including those from Cigna Global, offer "Global Health" modules. This is a massive perk for expats. It means if you are diagnosed with a serious condition, you have the option to seek a second opinion or even undergo treatment in your home country or at a world-leading facility in London or New York. The Norwegian public system is excellent, but it is focused on providing the best care within Norway. For some, the peace of mind that comes with global options is worth every krone.
Navigating the Challenges: Pre-existing Conditions and Exclusions
It is not all sunshine and rainbows in the private sector. The biggest hurdle for many expats is the "Pre-existing Condition" clause. Unlike the public system, which must take you as you are—chronic illnesses, previous surgeries, and all—private insurers are businesses. If you move to Norway with a history of back pain, don't expect a new private policy to cover a back operation six months later.
This is a significant point of frustration for many. Some expats buy private insurance expecting it to cover ongoing health issues, only to find the fine print excludes exactly what they need help with. This is why many veteran expats suggest a "Hybrid Approach." They use the public system for their known, chronic issues (leveraging the Understanding the Frikort: The 2026 Healthcare Exemption Card Limit) and keep a private policy for "new" issues that might arise.
For those who move frequently, SafetyWing can be a helpful alternative as their products are often designed with the mobile professional in mind, though you must still read the policy wording regarding pre-existing conditions carefully. If you are looking for a policy that can potentially cover pre-existing conditions after a moratorium period, a more robust international plan like those from Cigna Global might be your best bet, though the premiums will reflect that level of coverage.
Is Private Insurance Worth It for Families?
If you have children, the equation shifts again. In Norway, children under 16 receive almost entirely free healthcare. This includes GP visits, specialists, and even dental care. You can read more about this in our guide to Family Health in Norway: Pregnancy, Childbirth, and Pediatric Care. Because the public system prioritizes children, the waiting times for pediatric specialists are generally much shorter than they are for adults.
However, many parents still opt for private coverage for their kids to avoid any potential delay in developmental assessments or minor surgeries (like ear tubes or tonsillectomies). The cost to add a child to a private policy is usually quite low, and for many parents, the "just in case" factor outweighs the cost.
Another aspect to consider is the impact of a parent’s health on the family. If a parent is stuck on a waiting list for a knee surgery and can’t take the kids to football practice or go on the weekend hike that is so central to Friluftsliv: Embracing the Norwegian Outdoors and "Right to Roam", the whole family suffers. In this sense, private insurance for the parents is often more valuable for the family unit than insurance for the children themselves.
The Verdict: Who Should Buy Private Insurance in Norway?
After years of living here and seeing both sides of the coin, I believe the answer to "Is it worth it?" depends entirely on your specific circumstances. There is no one-size-fits-all answer, but there are definitely patterns.
You should strongly consider private insurance if:
- Your job is physically demanding or your income relies on high productivity.
- You have a history of sports injuries or minor ailments that often require specialist attention.
- You value your time and the ability to book appointments without "gatekeeper" friction.
- You are an expat who travels often and wants coverage that follows you across borders (using Cigna Global).
- You are in a transition phase or are a digital nomad not yet fully covered by the public system (using SafetyWing).
You can probably skip private insurance if:
- You are generally very healthy and rarely see a doctor.
- You have a high tolerance for administrative delays and don't mind the public waiting lists.
- You are on a tight budget and are comfortable with the "worst-case scenario" protection the public system provides.
- Your employer already provides a robust policy (always check this first!).
At the end of the day, the Norwegian public system is a safety net, not a luxury service. It will keep you alive and healthy, but it won't always do it on your schedule. For many of us who moved here from more "instant-gratification" healthcare cultures, the peace of mind offered by private cover is less about the medicine and more about the control it gives us over our own lives in a foreign land.
Whether you choose to go private or stick with the public route, the most important thing is to understand your rights and how to navigate the system. Make sure you are registered with a GP, keep an eye on your Helsenorge account, and don't be afraid to advocate for yourself. Norway is a wonderful place to live, and having a solid healthcare plan in place—whatever that looks like for you—is the first step to truly feeling at home. If you are still unsure about the specifics, I highly recommend reading Do I Need Private Health Insurance if I Live in Norway? for a deeper dive into the legal and practical requirements for your specific visa type.
Disclaimer
The information provided in this article is for general informational purposes only and does not constitute professional medical or legal advice. Healthcare laws, insurance policies, and public system regulations in Norway are subject to change. Always consult with the Norwegian Health Economics Administration (Helfo), the Norwegian Directorate of Health, or a qualified insurance professional before making decisions about your medical coverage. Be sure to read the specific terms and conditions of any private insurance policy, including those from Cigna Global or SafetyWing, as coverage limits and exclusions apply.