Debt Registers (Gjeldsregisteret): How Banks Check Your Unsecured Loans
One of the most stressful moments for any expat in Norway is standing in the middle of a high-stakes bidding war for an apartment, only to have your bank pull back your financing at the last second. This often happens because of a hidden financial footprint you didn't even know you were leaving. This guide explains how Gjeldsregisteret—Norway’s debt register—tracks your unsecured loans and why even an unused credit card can ruin your chances of homeownership.
Understanding the Role of Gjeldsregisteret in Norway
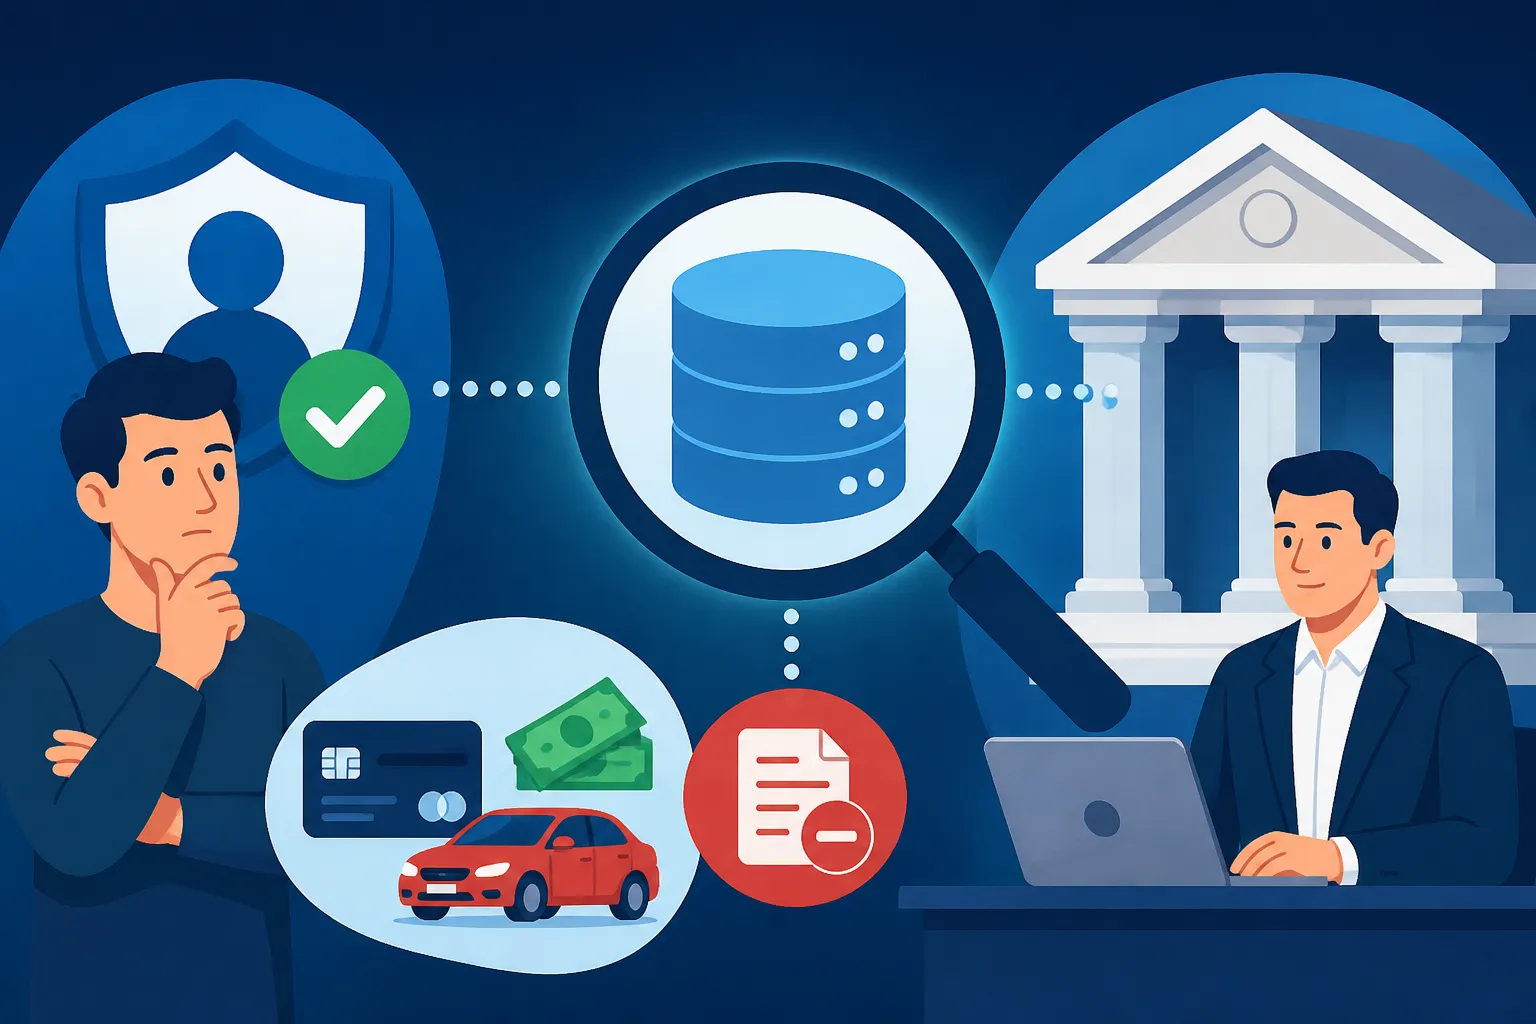
For many of us who moved to Norway from countries with different credit reporting systems, the transparency of the Norwegian system can be a shock. In many places, your credit score is a mysterious number that fluctuates based on secret algorithms. In Norway, the focus is less on a "score" and more on a cold, hard list of exactly how much you owe—or have the potential to owe. This is where Gjeldsregisteret comes in. Established relatively recently to combat the growing problem of consumer debt, this register is a centralized database where all financial institutions must report your unsecured debt.
Before this register existed, people could technically apply for multiple consumer loans on the same day from different banks, and the banks wouldn't see the other applications in real-time. That led to a lot of financial "over-steering" where individuals took on more than they could handle. Now, the second you are granted a credit limit, it appears in the register. Many newcomers assume that if they don't use their credit card, it doesn't count. In Norway, that logic is unfortunately reversed. The register exists to show banks your "debt potential," not just your current balance.
This transparency is a double-edged sword. On one hand, it makes Banking in Norway: How to Open an Account as a Foreigner much more structured because the bank doesn't have to guess about your external liabilities. On the other hand, it means your financial life is an open book. If you’ve been using services like Wise to move money around or manage international expenses, you know the value of transparency, but Gjeldsregisteret takes it to a level that feels very personal and, at times, invasive for those used to more privacy.
The Difference Between Secured and Unsecured Debt
It is vital to understand that Gjeldsregisteret does not track every single krone you owe. Its primary focus is on "unsecured" debt. To put it simply, this is debt that isn't backed by an asset like a house or a car. If you fail to pay a consumer loan, the bank doesn't have a specific item they can easily seize and sell to get their money back. Because of this higher risk, the interest rates are higher, and the Norwegian government wants to monitor this specific type of debt very closely.
When you look at Credit Cards and Loans: Building a Credit Score in Norway, you will see that unsecured debt is the biggest red flag for lenders. Secured debt, like a mortgage, is handled differently and is typically found through a different lookup in the National Registry or through your annual tax return. Gjeldsregisteret is the "fast-moving" database that banks check when you apply for any new credit. It includes credit cards, revolving credit (like "buy now, pay later" schemes), and personal consumer loans.
I remember helping a friend who was struggling to understand why her car loan was rejected despite having a great salary. It turned out she had three different store credit cards from electronics shops that she hadn't used in years. Each had a 30,000 NOK limit. Even though her balance was zero, Gjeldsregisteret told the bank she had 90,000 NOK in potential debt. When the bank calculated her ability to pay for Owning a Car in Norway: Insurance, EU Inspections (EU-kontroll), and Tolls, those ghost numbers were enough to tip the scales against her.
How the 5x Debt-to-Income Rule Impacts You
Norway has very strict lending regulations designed to prevent a housing bubble. One of the most famous (or infamous) rules is that your total debt cannot exceed five times your gross annual income. This is a hard ceiling for most banks. When a bank calculates this, they don't just look at the mortgage you are asking for; they look at every single bit of debt reported in Gjeldsregisteret.
If you earn 600,000 NOK a year, your maximum total debt is 3 million NOK. If you have a consumer loan of 100,000 NOK and credit card limits totaling 50,000 NOK, your available "space" for a mortgage isn't 3 million—it's 2.85 million. This is a massive detail that many expats miss when they are Buying Property in Norway: Bidding Wars, Mortgages, and Rules. In a market as competitive as Oslo or Bergen, that 150,000 NOK difference can be the reason you lose out on a home.
| Debt Type | Recorded in Gjeldsregisteret | How it Affects Your Borrowing Power |
|---|---|---|
| Credit Card (Unused) | Yes (The Full Limit) | Reduced by the full limit amount |
| Credit Card (Used) | Yes (The Full Limit) | Reduced by the full limit amount |
| Consumer/Personal Loan | Yes (Remaining Balance) | Reduced by the balance + interest |
| "Buy Now, Pay Later" | Yes (Total Granted) | Often counts as a full credit limit |
| Mortgage | No (Found elsewhere) | Part of the 5x income calculation |
| Student Loan (Lånekassen) | No (Found elsewhere) | Part of the 5x income calculation |
It is also worth noting that the banks assume a very high interest rate when they "stress test" your debt. They don't just check if you can afford the debt today; they check if you could afford it if interest rates rose by several percentage points. This is why Cost of Living in Norway 2026: Budgeting for Singles and Families is so heavily influenced by how you manage your unsecured credit. Every small credit line you open is a weight on your financial flexibility.
The Unused Credit Limit Trap
This is the most common pitfall for foreigners in Norway. In many countries, having a high credit limit that you don't use is seen as a sign of financial stability—it shows that banks trust you with money. In the eyes of a Norwegian mortgage advisor, however, an unused credit limit is an "accident waiting to happen." They see it as 50,000 NOK that you could spend tomorrow on a vacation, which would then interfere with your ability to pay your mortgage.
When you are preparing to apply for a loan, the best thing you can do is log into the debt register and start closing accounts. Don't just pay them off; you must actually contact the bank and ask them to terminate the credit agreement and delete the credit limit. It can take a few days for the register to update, so don't wait until the day of your mortgage meeting to do this. Some people have lost their dream homes because they forgot about a "free" credit card they signed up for just to get a discount on a flight years ago.
Managing these small details is part of the broader challenge of Filing Your Tax Return (Skattemelding): Deadlines and Common Deductions. While the debt register is separate from your taxes, the numbers eventually meet on your tax return. If you have significant debts, you might get a tax deduction on the interest, but that doesn't outweigh the negative impact those debts have on your "Låneramme" (borrowing limit). For those with complex international tax situations, using a service like Taxes for Expats can help clarify how these local Norwegian debts interact with your obligations back home.
Accessing Your Data via BankID
The good news is that you have full access to see exactly what the banks see. In the spirit of Norwegian "Digitalsering," you can log into the debt registers (there are a few licensed ones, like Norsk Gjeldsinformasjon or Gjeldsregisteret AS) using your BankID. This is one of the many reasons why BankID Explained: Norway's Digital Identity System and Expat Challenges is the most important article for any new arrival to read. Without BankID, managing your financial reputation in Norway is incredibly difficult.
Once you log in, you will see a list of every financial institution that has reported a debt or a credit limit in your name. If you see something that looks wrong—perhaps a loan you've already paid off or a credit card you thought you closed—you cannot ask the register to fix it. You must contact the specific bank that reported the data. The register is just a mirror; if the bank is holding a dirty cloth, the mirror will show a smudge.
It is wise for expats check their status at least once a year, even if they aren't planning to buy a house. Identity theft is rare in Norway but not impossible, and seeing an unknown 50,000 NOK loan on your profile is the fastest way to catch a problem. This is especially important when you are Understanding Your Skattekort (Tax Deduction Card) and How to Change It, as your debt levels influence your tax brackets and wealth tax calculations.
Managing Debt as an Expat
If you find yourself with too much unsecured debt, the Norwegian "refinansiering" (refinancing) market is very active. This essentially means taking out one large loan with a lower interest rate to pay off several smaller, expensive ones. However, as an expat, you might face stricter requirements. Banks often want to see at least three years of tax history in Norway before they offer the best rates for consolidation.
If you are moving money from abroad to pay down Norwegian debt, using a service like Wise is often the most cost-effective way to avoid the high currency exchange fees charged by traditional Norwegian banks. Every krone you save on fees is a krone that can go toward clearing your register profile. Being proactive about this shows the bank that you understand the Norwegian system and are committed to staying here long-term.
Remember that your financial behavior in Norway is tracked much more efficiently than you might be used to. While there is no "permanent record" in the way some people fear, Gjeldsregisteret is a very real and very influential part of your life here. If you are struggling with the cultural shift of how money is managed, don't be afraid to talk to a financial advisor at your bank. They are generally quite helpful and would rather help you clean up your debt profile now than reject your mortgage application later.
Final Steps Before a Loan Application
Before you walk into a meeting with a "Saksbehandler" (case officer) at DNB or Nordea, you should have a "clean" Gjeldsregisteret report. This means closing all unnecessary credit cards, even the ones with "good" benefits, and paying down any consumer loans as much as possible. If you have a "samboer" (cohabitant) and you are applying together, they need to do the same. The bank will check both of you, and one person's forgotten credit card can lower the combined borrowing power for both.
Check the register. Close the accounts. Wait for the update. Then, and only then, should you start looking at houses on Finn.no. The peace of mind that comes from knowing exactly what the bank will see is worth the few hours of administrative work it takes to tidy up your digital financial life.
Disclaimer
This article is for informational purposes only and does not constitute professional financial or legal advice. Regulations regarding debt registers and lending practices in Norway can change frequently. You should always consult with a qualified financial advisor or contact the Norwegian authorities (Skatteetaten or UDI) for the most up-to-date information regarding your specific situation. The author is an expat sharing personal experiences and research, not a licensed financial consultant.