What Does Innboforsikring (Home Contents Insurance) Actually Cover?
Navigating the labyrinth of Norwegian insurance policies can feel like trying to find your way through a blizzard without a map, especially when it comes to understanding what exactly "Innboforsikring" covers. Many of us expats arrive, secure a place, and might overlook this crucial piece of the puzzle, only to wonder what would happen if a pipe bursts or our prized possessions go missing. This guide aims to demystify home contents insurance in Norway, detailing what it protects, what it doesn't, and why it's an essential part of settling into your new Norwegian home.
What Exactly is Innboforsikring in Norway?
Innboforsikring, literally translated as "contents insurance," is a type of insurance policy designed to protect your personal belongings within your home against a variety of unforeseen events. Unlike "Boligforsikring" (building insurance), which covers the structure of the house itself, Innboforsikring is all about what's inside – your furniture, electronics, clothing, decor, and personal items. It's often misunderstood, especially by those from countries where home insurance might combine both building and contents, but in Norway, they are typically distinct, and for renters, Innboforsikring is your main focus.
Beyond Just Your Sofa: Understanding "Innhold"
When an insurance company talks about "innhold" (contents), they're not just thinking about your sofa, dining table, or bed. They’re referring to virtually everything you own that isn't permanently fixed to the building. Imagine turning your home upside down: anything that falls out is generally considered "innbo" or contents. This includes obvious things like your TV, computer, and kitchen appliances that aren't built-in. But it also extends to your clothes, books, sentimental photographs, sports equipment, and even the food in your fridge and pantry. For many expats, the sheer value of accumulated personal items often far exceeds what they initially estimate, making a proper understanding of "innhold" crucial for adequate coverage.
Let's say you've painstakingly moved all your treasured belongings from your home country, perhaps using a reliable international moving service. The combined value of these items, from your grandmother's antique lamp to your specialized camera gear, can quickly add up. Without Innboforsikring, if these items are damaged or stolen, you'd be looking at replacing them entirely out of pocket, which can be a staggering financial blow. It's about protecting the tangible elements that make your house a home, ensuring that a disaster doesn't also become a financial catastrophe for your personal life.
The Mandatory vs. Highly Recommended Reality
While it might not be legally mandatory in Norway for renters to have Innboforsikring, it is almost universally considered highly recommended, bordering on essential. Most landlords will strongly advise you to get it, and some might even include a clause in the rental agreement suggesting or requiring it, though enforcing it can be tricky. However, the real "mandatory" aspect isn't a government decree but rather the stark reality of financial risk.
Think about it: if you live in a rented apartment, your landlord's building insurance (Boligforsikring) covers the walls, roof, and fixed installations – not your personal possessions. If there's a fire, a flood, or a break-in, their insurance will rebuild the apartment, but it won't replace your stolen laptop, your burnt clothing, or your water-damaged furniture. This is where your Innboforsikring steps in. For homeowners, it’s also critical because while your Boligforsikring protects the house structure, it won't cover the contents unless you have a combined policy or a separate Innboforsikring. Overlooking this distinction is a common trap many new arrivals fall into, assuming one covers the other. It's a small monthly cost that can save you from a huge financial headache down the line. To learn more about how this fits into the broader picture, you might want to look into topics like Mandatory Insurance in Norway: Home Contents (Innboforsikring) and Auto.
Key Coverages You Can Expect from Innboforsikring
One of the greatest benefits of Innboforsikring is its comprehensive nature, typically covering a wide array of incidents that could damage or destroy your personal property. These policies are designed to offer peace of mind, knowing that common perils and even some less common ones are addressed.
Damage from Fire, Water, and Natural Disasters
These are often the foundational pillars of any Innboforsikring policy. Norway, with its sometimes unpredictable weather and older building stock in urban areas, presents specific risks that make these coverages particularly vital.
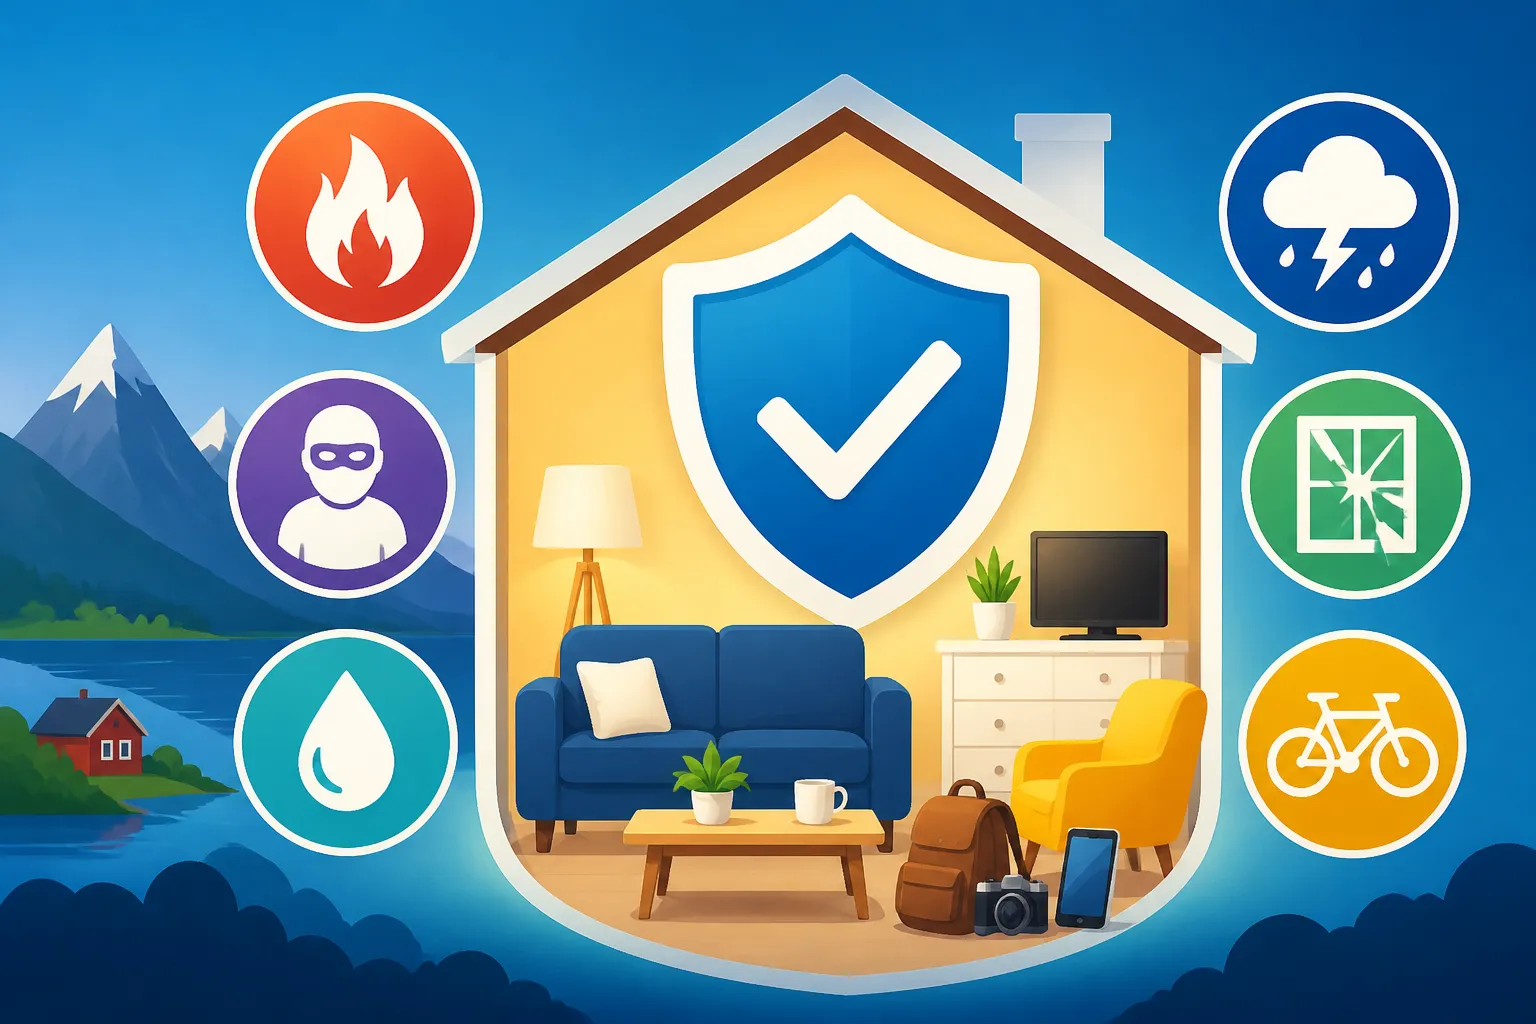
- Fire: This covers damage caused by fire, smoke, and even extinguishing efforts. If your apartment building has a fire, whether it starts in your unit or a neighbor's, your Innboforsikring will typically cover the cost of replacing your damaged belongings. This also usually extends to damage from lightning strikes.
- Water Damage: This is a surprisingly common claim. Think about a burst pipe in your building, a leaking roof during heavy rain, or even an overflowing washing machine. Water damage can be insidious and incredibly destructive to furniture, electronics, and personal documents. Most policies will cover sudden and unforeseen water leaks, but usually not gradual damage from long-term neglect (more on that later). Given Norway's climate, with heavy rainfall and snowmelt, understanding this coverage is particularly important.
- Natural Disasters: Events like storms, floods (from rivers/lakes, not typically just surface water), landslides, and avalanches are also generally covered. While less frequent, these events can cause catastrophic damage, and having your personal effects protected against the forces of nature provides significant reassurance. Living in a fjord region or near a river, for example, makes this coverage especially relevant.
Theft and Vandalism – Both Home and Away
The fear of a break-in is a common concern, and Innboforsikring provides a crucial safety net. It covers your belongings if they are stolen from your home, as well as any damage caused during the burglary (e.g., a broken window or forced door). This includes not only obvious items like electronics and jewelry but also less obvious ones like expensive clothing or specialized tools.
However, many Norwegian Innboforsikring policies go a step further and offer limited coverage for theft of your belongings outside your home. This is often an overlooked but incredibly valuable feature. For instance, if your laptop is stolen from a cafe in Oslo while you're working, or your phone is snatched from your pocket on a crowded street, your Innboforsikring might cover a portion of the replacement cost, typically up to a certain sum (e.g., 20,000 NOK). The exact limits and conditions vary by policy, so it’s always wise to check the fine print. This 'away-from-home' coverage can also extend to items stolen from a locked car or a hotel room while traveling, although often with higher deductibles or lower limits. This broader scope differentiates it from just basic home coverage.
Personal Liability (Ansvarforsikring)
This is one of the most critical, yet often least understood, components bundled with most Innboforsikring policies. Personal liability insurance, or "ansvarforsikring," protects you financially if you accidentally cause damage to someone else's property or injure another person. This isn't about your possessions; it's about your responsibility for damages to others.
Consider these scenarios:
- You accidentally leave the tap running, causing water damage to the apartment below you.
- Your child breaks an expensive item at a friend's house.
- You're cycling and accidentally collide with a pedestrian, causing them injury.
In such cases, the costs can be substantial, and your personal liability coverage within your Innboforsikring will step in to cover the damages or medical expenses. The coverage typically extends to you and your immediate family members living in the same household. For expats, this is particularly reassuring, as understanding complex liability laws in a new country can be daunting. It’s a peace-of-mind clause that protects your personal finances from unexpected legal claims.
Legal Assistance and Identity Theft Protection
Many modern Innboforsikring policies in Norway now offer supplementary benefits that extend beyond traditional damage and theft. These can be incredibly useful additions for expats navigating a new legal and digital landscape.
- Legal Assistance (Rettshjelp): This benefit typically covers a portion of your legal expenses if you find yourself in a dispute that falls under civil law. For example, if you have a disagreement with a neighbor about property boundaries, or a contractual dispute related to a personal purchase, your insurance might cover legal fees up to a certain amount, after a deductible. This can be invaluable in a country where legal services are expensive, and language barriers can complicate matters. It's not for criminal cases, but for civil matters, it can prevent minor disagreements from spiraling into major financial burdens.
- Identity Theft Protection: In our increasingly digital world, identity theft is a growing concern. Some Innboforsikring policies now include coverage to help you recover if your identity is stolen. This could involve assistance with credit monitoring, legal advice, and covering expenses related to restoring your identity. As expats often deal with new forms of identification and online services (like BankID, which is essential for almost everything here), this can be a valuable layer of protection against digital threats. Keeping your finances secure is paramount, and understanding your exposure, including potential identity theft, is key. If you're managing your finances in Norway, you might also be looking at Taxes for Expats as another complex area.
What Innboforsikring Typically Doesn't Cover (And Why It Matters)
While Innboforsikring is comprehensive, it's not a magic shield against all misfortunes. Understanding its limitations is just as crucial as knowing what it covers, preventing unpleasant surprises when you need to make a claim.
Wear and Tear, Poor Maintenance, and Expected Damage
Insurance is generally designed to cover sudden, unforeseen events, not the natural deterioration of items or damage resulting from neglect.
- Wear and Tear: Your washing machine eventually breaking down due to age, your sofa springs wearing out, or your phone screen gradually acquiring scratches are not typically covered. These are considered normal wear and tear, part of the life cycle of any possession.
- Poor Maintenance/Neglect: If a water leak occurs because you failed to fix a clearly visible issue for months, or if mold develops due to consistently poor ventilation, the insurance company might deny your claim. They expect you to reasonably maintain your property and mitigate foreseeable risks. This is why when you're thinking about Renting in Norway: Apartments, Contracts, and Tenant Rights, understanding your responsibilities as a tenant for minor maintenance is important.
- Expected Damage: Damage that is a direct consequence of an item's intended use or a known defect that you ignored is usually excluded. For example, spilling coffee on your laptop due to your own clumsiness or dropping your phone is often not covered unless you have specific accidental damage add-ons.
These exclusions highlight the importance of reading your policy details thoroughly. While frustrating, these limitations are standard across most insurance products globally, designed to prevent abuse and keep premiums affordable for genuine unforeseen incidents.
High-Value Items Requiring Special Coverage
Many Innboforsikring policies have limits on the value of individual items or categories of items that they will cover. While your general contents are covered up to the sum insured, specific high-value items might fall into special categories with lower sub-limits.
- Jewelry, Watches, and Precious Metals: These often have a low individual item limit or a collective limit for all such items. If you have an expensive engagement ring or a collection of valuable watches, you might need to list them separately on your policy or take out a special "verdigjenstandsforsikring" (valuable item insurance) to ensure full replacement value.
- Art and Collectibles: Similarly, valuable artwork, antique furniture, or extensive collections might exceed standard Innboforsikring limits. An appraisal and separate endorsement or policy are often required.
- Specialized Equipment: High-end camera gear, musical instruments, or sports equipment can also be subject to limits. If you're an avid photographer with thousands of NOKs worth of lenses, ensuring they're properly insured is key.
It’s crucial to declare such items to your insurance provider and discuss if additional coverage is needed. Don't assume your general policy will cover the full cost of replacing your 50,000 NOK diamond necklace if it's stolen. This is particularly relevant for many expats who might have brought valuable heirlooms or specialized equipment with them.
Your Building Itself: Differentiating from Boligforsikring
This is perhaps the most fundamental distinction that often confuses new arrivals. Innboforsikring covers your personal possessions. Boligforsikring (building insurance), on the other hand, covers the physical structure of the building you live in – the walls, roof, floors, fixed installations like plumbing and electrical wiring, and often permanent fixtures like built-in kitchen cabinets and bathroom suites.
- For Renters: If you are renting an apartment, your landlord is responsible for having Boligforsikring. You, as the tenant, are responsible for your own Innboforsikring. If a pipe bursts and damages the structure of the apartment, the landlord's Boligforsikring covers the repairs. If that same burst pipe damages your furniture, your Innboforsikring covers your personal items. It’s a clean separation of responsibilities.
- For Homeowners: If you own your home (whether it’s an apartment in a "borettslag" or "sameie," or a detached house), you must have Boligforsikring. In many cases, especially for detached houses, you'll get a combined policy that includes both building and contents. For apartments in housing cooperatives, the cooperative often has a collective building insurance, and you, as the owner, might only need to ensure your contents. However, always verify this with your cooperative or "sameie." Understanding Buying Property in Norway: Bidding Wars, Mortgages, and Rules will reveal the critical nature of comprehensive property insurance.
Failing to understand this difference can leave you either uninsured for your personal items as a renter or facing significant structural repair costs as a homeowner if you only focused on contents.
Practicalities: Choosing Your Policy and Making a Claim
Getting Innboforsikring sorted is a fundamental part of setting up your life in Norway. It's not just about picking the cheapest option; it's about finding the right balance of coverage and cost for your specific situation.
Factors Influencing Your Premium
Several elements play a role in how much you'll pay for your Innboforsikring. Being aware of these can help you make an informed choice and potentially lower your costs.
- Sum Insured (Forsikringssum): This is the maximum amount your insurance company will pay out for all your belongings if they are completely destroyed. You need to estimate the total replacement value of all your possessions. Undervalue this, and you risk not being fully compensated. Overvalue it, and you'll pay higher premiums unnecessarily. Most insurance companies offer calculators to help you estimate this, or a standard amount per square meter.
- Deductible (Egenandel): This is the amount you pay out of pocket before your insurance coverage kicks in for a claim. A higher deductible usually means a lower monthly premium, and vice-versa. It's a trade-off: save money monthly but pay more per incident, or pay more monthly for less out-of-pocket during a claim.
- Location: Where you live in Norway can affect your premium. Areas with higher crime rates or greater risks of natural disasters (e.g., coastal areas prone to storms, or specific flood zones) might have slightly higher premiums.
- Type of Dwelling: An apartment in a large complex might have different risks than a detached house, affecting rates. Security measures like burglar alarms can sometimes lead to discounts.
- Chosen Coverage Level: Many insurers offer basic, standard, and premium packages. Higher tiers might include more comprehensive accidental damage, travel insurance elements, or higher limits for specific valuables.
It's wise to compare offers from different providers like If, Gjensidige, Fremtind, and Tryg. Don't hesitate to use comparison websites to get multiple quotes, and check if you can get a discount for bundling other insurances like car or travel insurance with the same provider. Remember to budget for these ongoing costs when planning your Cost of Living in Norway 2026: Budgeting for Singles and Families.
The Importance of Accurate Valuation
Estimating the total value of your belongings (your "forsikringssum") is probably the most crucial step when setting up your Innboforsikring. It can feel daunting, but it's essential to get it right.
- Take Inventory: The best way to do this is to walk through your home, room by room, and make a list of everything. Don't forget items in storage, in your shed, or in your basement "bod."
- Estimate Replacement Cost: For each item, think about how much it would cost to buy a new equivalent item today, not what you paid for it or its depreciated value. This is typically what insurance policies cover – "nyverdi" (new value) or "gjenanskaffelsesverdi" (replacement value).
- Document Everything: Take photos or videos of your belongings. Keep receipts for major purchases. This documentation is invaluable if you ever need to make a claim.
- Consider Special Items: As discussed, for high-value jewelry, art, or specialized equipment, ensure you have appraisals and discuss specific coverage with your insurer.
Many expats significantly underestimate the value of their household contents. A simple three-room apartment can easily hold 300,000 to 500,000 NOK worth of furniture, electronics, clothing, and personal effects. While most Norwegian policies offer generous automatic sums for typical households, it's always best to customize if you have particularly valuable items or a lot of possessions.
Navigating the Claims Process (Skademelding)
If the unfortunate happens and you need to use your Innboforsikring, the claims process (often initiated by a "skademelding" or damage report) is fairly standardized, but preparation helps.
- Safety First: If it's a fire or severe water damage, ensure safety and contact emergency services (110 for fire, 112 for police, 113 for medical emergencies) immediately if needed. For non-emergencies, you'd contact services like a plumber or locksmith.
- Contact Your Insurer: Report the incident to your insurance company as soon as reasonably possible. Many have online portals or dedicated phone lines for claims. Be prepared to provide your policy number and details of the incident.
- Document the Damage: Take extensive photos and videos of the damage before cleaning up or making repairs, if safe to do so. This visual evidence is critical.
- Gather Evidence: For theft, you'll need a police report. For water damage, notes on what happened, and any plumber's reports. For damaged items, receipts or proof of purchase will help establish value.
- Fill Out the Skademelding: The insurance company will provide a form to detail the incident, the items affected, and the estimated costs. Be thorough and honest.
- Assessment and Settlement: An insurance adjuster might visit your home to assess the damage. Based on their assessment and your documentation, they will process your claim. You'll typically pay your deductible, and the insurer will cover the rest up to your policy limits.
Making sure your documentation is in order can significantly speed up the process. Keep records of all communication with your insurance company. Remember, whether you're paying your initial premium or receiving a payout, handling international financial transfers can be complex, and services like Wise can sometimes make it easier to manage funds if you have accounts in multiple currencies. For instance, if you're managing payments related to Setting Up Utilities: Electricity, Heating, Internet, and Mobile Plans or making a larger payment for a claim, a service like Wise can offer competitive exchange rates. Similarly, understanding the costs associated with Moving Out Checklist: Cleaning Standards (Utvask) and Deposit Return will help you align your insurance with typical end-of-lease expectations.
Disclaimer
Please remember that I am a veteran expat blogger offering general advice, not a licensed financial advisor or insurance agent. Insurance policies and legal frameworks in Norway can change. Always consult directly with an authorized Norwegian insurance provider for the most accurate and up-to-date information regarding your specific situation and needs. This guide is for informational purposes only.